« BACK TO BLOG
Market Intel, Forecasts & Strategies
Metro Atlanta Retail | 2026 Q3 Recap and What to Look Out for in Q4
Metro Atlanta Retail | 2026 Q3 Recap and What to Look Out for in Q4
Q3 brought a clear shift in Metro Atlanta retail activity: transaction volume normalized from Q2, average deal size expanded, cap rates held firm, and historically low vacancy (~4.0%) drove average asking rents to $22.32 per square foot. The following update breaks down where capital moved, how pricing held, which tenants were active, and what those trends mean heading into Q4.
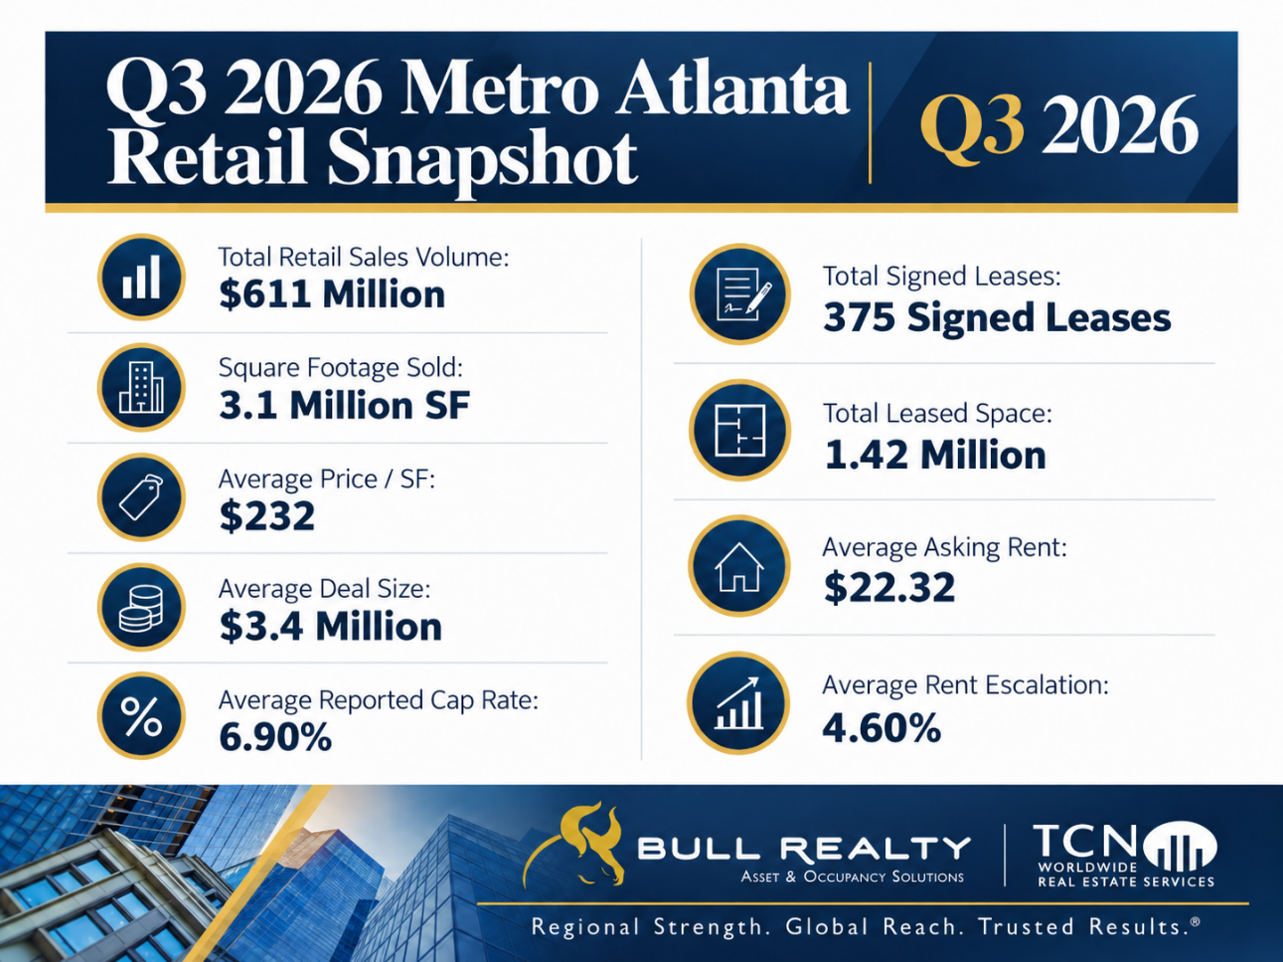
Retail investment sales totaled $611 million across 3.1 million square feet in Q3. The average transaction price reached $3.4 million, with average pricing settling at $232 per square foot and reported cap rates holding firm at 6.9%. Assets trading during the quarter achieved an average of 93.8% of their original asking price, with an average marketing period of 8.5 months. Private buyers accounted for 73% of sales volume within a buyer pool that was 83% national and 17% local.
Investment Volume & Pricing Execution
While Q2 experienced an extraordinary spike driven by portfolio-level institutional closings ($948 million across 4.3 million square feet), Q3’s $611 million in sales volume outpaced Q1’s $590 million baseline. With new retail construction remaining near historical lows, capital deployment across Metro Atlanta concentrated heavily into larger retail acquisitions.
Pricing discipline underscores this stability. Average pricing settled at $232 per square foot, a $17 per square foot gain over Q1, while cap rates remained anchored at 6.9% for the third consecutive quarter. Most significantly, Q3’s average transaction price expanded to a year-to-date peak of $3.4 million (up from $2.9 million in Q2 and $2.4 million in Q1). This upward shift in capital allocation per transaction was reflected in several significant Metro Atlanta retail acquisitions, including Heritage Hills, which traded on August 4th for $30.40 million ($128.52/SF across 236,548 SF); Merchants Walk on Johnson Ferry Rd in Marietta, which closed on July 21st for $93.2 million ($342.66/SF across 271,992 SF); and the newly constructed Shops at Indian Creek at 4518 GA-42, which closed on August 13th for $23.70 million ($489.82/SF across 48,387 SF GLA).
Deal execution metrics further highlight seller pricing leverage. Q3 Metro Atlanta transactions achieved an average ask-to-close realization of 93.8% of asking price, outperforming both Q2 (90.8%) and Q1 (93.0%), with marketing periods averaging 8.5 months compared to 10.8 months in Q1.
Leasing Fundamentals
Metro Atlanta leasing fundamentals remained robust through Q3, recording 375 signed retail leases totaling 1.42 million square feet. While transaction volume adjusted from 468 deals in Q2, total leased square footage held comparatively firm, supported by a 16.7% expansion in average deal size to 3,777 square feet. This shift toward larger tenant footprints was driven by major anchor backfills, including EOS Fitness executing 66,500 square feet in September at Perimeter Village Shopping Center (4725 Ashford Dunwoody Rd) in a former Walmart space, The Pickle Pad signing 48,220 square feet in August at Olde Mill Shopping Center (3101 Roswell Rd) in the former Walmart Neighborhood Market space, and PoKiddo (a major global franchise and manufacturer of massive indoor trampoline and adventure parks) taking 42,000 square feet in July at Fayetteville Pavilion (250 Pavilion Pkwy) in the former JOANN space.
With new construction starts remaining near historic lows (approximately 0.2% of total inventory), Metro Atlanta landlords maintain substantial pricing leverage, prioritizing aggressive contract terms and escalation structures over concession packages. Average asking rent advanced to $22.32 per square foot, average lease duration extended to 5.9 years, and annual contractual rent escalations climbed from 3.5% in Q2 to 4.6% in Q3.
This step-up to a 4.6% average escalation structure across an average 5.9-year lease term expands forward yield profiles across Metro Atlanta assets. Capturing an additional 110 basis points in annual rent growth generates over $2.65 per square foot in cumulative top-line NOI expansion over a five-year hold, driving terminal valuation growth and strengthening debt-coverage ratios entering Q4.
Q4 Outlook
As Metro Atlanta enters Q4, near-zero construction starts (~0.2% of total inventory) and persistent tenant demand will continue to support landlord pricing leverage. Year-end capital deployment, annual acquisition targets and 1031 exchange deadlines should provide additional sources of buyer demand through Q4.
With new retail supply remaining exceptionally constrained, asking rents continuing to advance, and transaction cap rates holding at 6.9% for the third consecutive quarter, current market conditions favor reassessing asset valuations to capture active Q4 buyer demand before year-end.
To review an updated market valuation or analyze what your property or portfolio can achieve heading into Q4, contact me directly at 404-876-1640 x161 for a confidential assessment
National & Atlanta Intel
- Connolly Reveals First Tenants at Publix-Anchored Metro Atlanta Center
- Sterling Buys East Cobb’s Merchants Walk for $93.2M
- Furniture Retailer to Open at Major Georgia Shopping Center
Acquisition Opportunities
- Retail strip center in the Atlanta MSA totaling ±35,600 SF with100% leased. Diversified mix of restaurant, medical and service-oriented tenants and recent capital improvements, offered at $9.5M (approximately $267/SF) at a 6.3% cap rate.
- Retail strip center in a growing Atlanta-area submarket totaling ±16,979 SF with 100% leased. Service-oriented tenant mix and strong visibility along a major retail corridor, offered at $4.2M ($247/SF) at a 6.8% cap rate.
- Metro Atlanta neighborhood shopping center totaling ±102,437 SF with stable in-place income and a strong service-oriented tenant mix, offered at $6.2M ($61/SF) at a 9.5% cap rate.
Call 404-876-1640 x 161 for more information.
Recently Sold
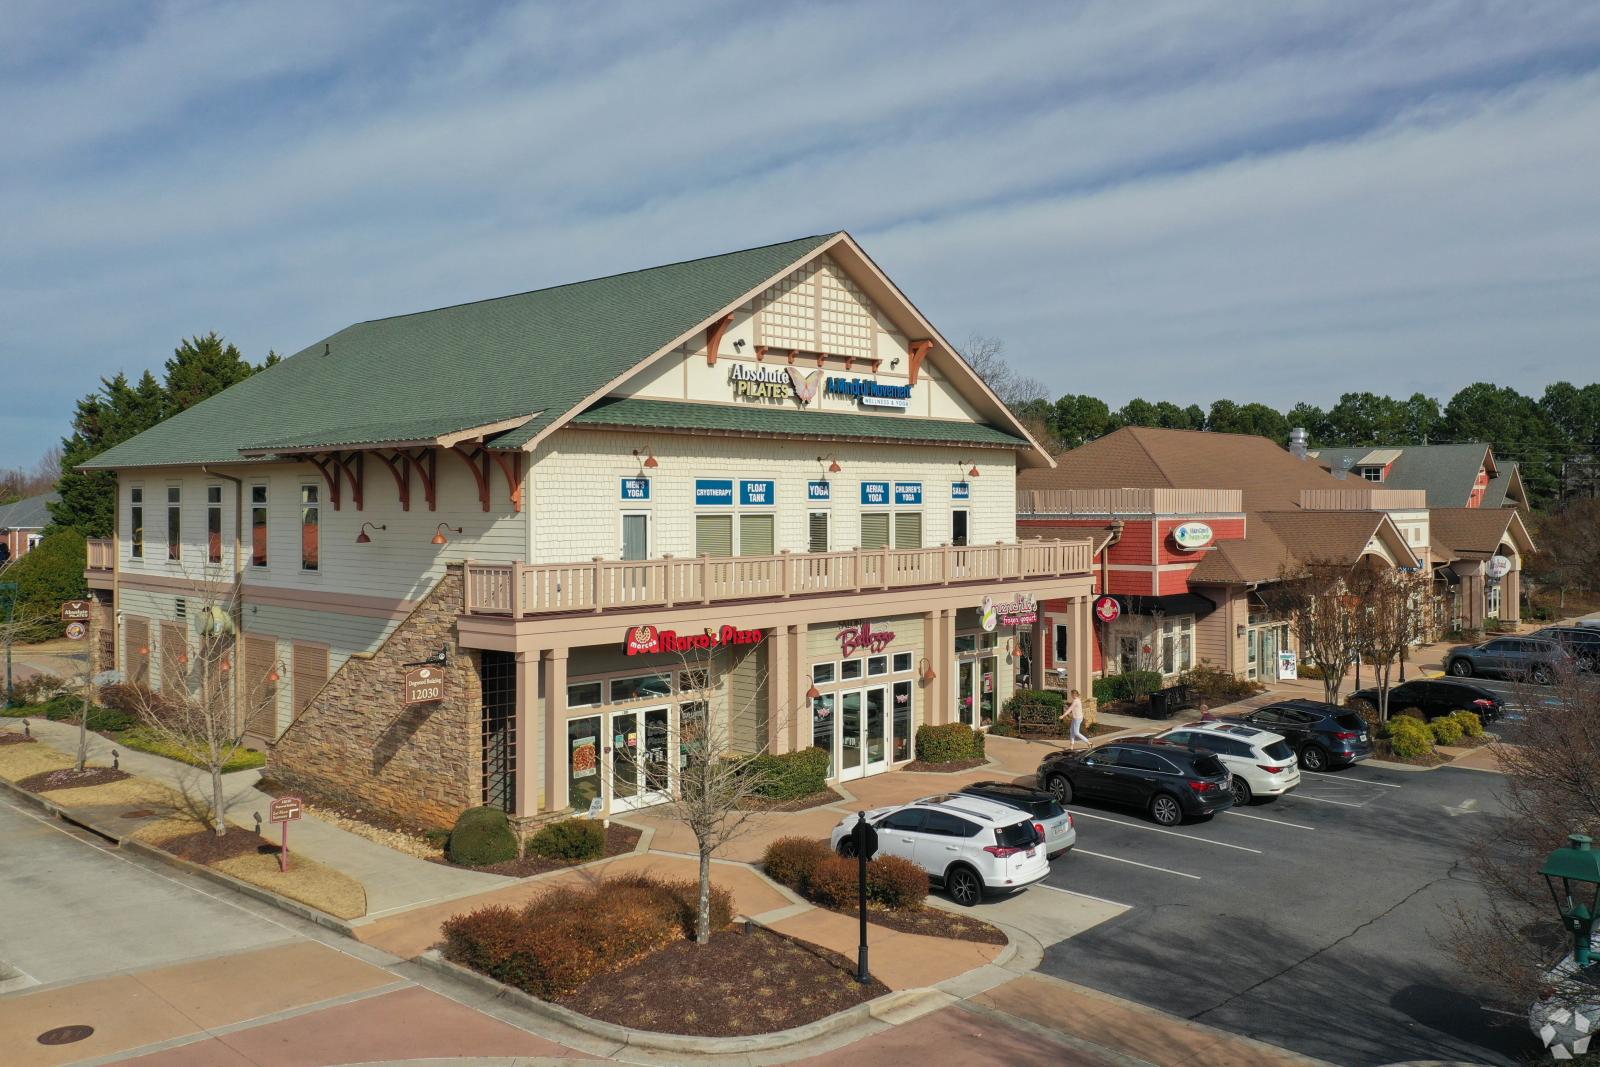
Sweet Apple Village
$20.3M | $325/SF | 6.35% Cap
Tower Plaza
$7.3M | $82/SF | 7.89% Cap
Chastain Corners
$4.9M | $816/SF | 6.1% Cap
Properties Wanted
- Unanchored retail strip centers of varying sizes and tenant mixes.
- Grocery-anchored shopping centers across the Southeast U.S.
- Multi-tenant retail centers with vacancy or near-term leasing upside.
|
|